Foreclosure Lists
  
Detached - N. Delta
Detached - Chilliwack, Sardis (1)
Attached - Surrey, S. Surrey
Detached - Langley, Cloverdale
Detached - Burnaby, New West (1)
Detached - N. Surrey, S. Surrey
Attached - Tri Cities (2)
Detached - Mission, Abbotsford (1)
Attached - Chilliwack, Sardis
Attached - Mission, Abbotsford (1)
Detached - Tri Cities (2)
Detached - Surrey
Attached - Pitt Meadows, Maple Ridge (1)
Detached - Pitt Meadows, Maple Ridge (1)
Attached - Burnaby, New West (1)
Attached - Langley, Cloverdale (1)
Bank of Canada Raises Interest Rate as Inflation Projected to Worsen
By Judy Trinh for CTV News
Updated: October 28, 2026 at 10:34a.m. EDT
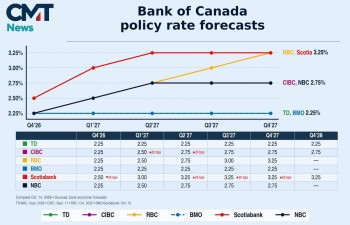
OTTAWA — OTTAWA - The Bank of Canada raised its policy interest rate by 25 basis points to 2.5 per cent. It’s the first hike since July 2023. The central bank wants to control inflation by reducing the risk that high fuel prices could spill over and seep into the overall economy.
In its October Monetary Policy Report, the BOC said the rise in energy prices and uncertainty surrounding Canada’s trade relationship with the United States are the two biggest risks to increasing costs of living.
In its report, the BOC said that high energy costs have not yet spread broadly to other prices, but “cost pressures are building and that businesses anticipate passing on more of their increased costs to customers.”
Inflation is currently at 3.1 per cent.
Tiff Macklem, the central bank’s governor, said that the outlook for inflation has “deteriorated” since the BOC’s July report.
“With the outlook for inflation substantially higher and the economy showing resilience, an increase in the policy rate is needed to reduce the risk that elevated energy prices could spill over and become generalized inflation,” Macklem said in prepared remarks during a Wednesday morning news conference.
Continue reading here...
CHIP Reverse Mortgages - A New Way Of Thinking About Mortgages For Seniors
A CHIP Reverse Mortgage is a mortgage loan for Canadian homeowners aged 55 and older that lets you convert up to 55% of your home equity into tax-free cash without having to sell or move. The lender, Home Equity Bank, is a Canadian chartered bank and is the fasted growing lender in Canada.
How It Works
No Payments: You do not make monthly mortgage or interest payments although you can make full or partial payments if you wish to. The interest owed on the mortgage simply accrues and is added to the mortgage balance each month.
You do not need to qualify for the mortgage on income, it is based on your home value, home location and your ages
Repayment: The loan is only paid back when you sell, move, or pass away.
Ownership: You keep complete ownership and control of your home.
Payout Options: You can get the cash as one lump sum or through scheduled advances.
Tax Status: The money you receive is tax-free and does not affect Old Age Security (OAS) or Guaranteed Income Supplement (GIS) benefits.
Key Rules and Protections
Eligibility: All owners and people on the home title must be at least 55 years old, and the property must be your primary residence.
Obligations: You must still pay your property taxes, keep home insurance, and maintain the property in good condition. No Negative Equity
Guarantee: You will never owe more than the fair market value of your home when it is sold.
Do you or someone you love have more questions about CHIP Mortgages? Call us today!
Office number: 604-534-6504
Want to text? Dedicated texting line: 236-233-3930 (available during regular business hours)
|